Просмотр новости
Найдите то, что Вас интересует
 Спутники
 РН
 SpaceX
 Роскосмос
 NASA
СпутникиРНSpaceXРоскосмосNASAHyperscale expansion drives 16% annual LNG demand growth in Southeast Asia through 2035, while India’s renewables-dominated grid shuts gas out entirely.
The hyperscale data centre boom sweeping Asia is generating materially divergent outcomes for LNG demand across the region, with Southeast Asia emerging as a compelling new demand driver while South Asia remains structurally out of reach for gas, according to new research from Wood Mackenzie.
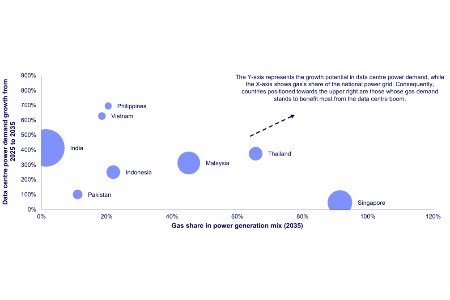
The report, Data Centres Bolster LNG Demand in Southeast Asia, Not South Asia, finds that Southeast Asia’s data centre pipeline is set to more than triple from 2.8 gigawatts (GW) to 9.4 GW by 2035, with electricity demand from data centres growing from 17 terawatt-hours (TWh) to 57 TWh over the same period. Combined-cycle gas turbines (CCGT) are currently the most viable technology capable of meeting data centres’ 24/7 reliability requirements at scale, as grid-scale battery storage remains commercially immature across the region through the mid-2030s.
Md Fadhlullah Omarali, principal analyst at Wood Mackenzie said “ what makes data centre demand interesting from an LNG perspective is the counterparty profile. These are large, creditworthy off-takers with power needs that remain stable regardless of economic cycles. That does change the risk of calculus for new supply into Southeast Asia.”
Southeast Asia: a new structural demand signal
The LNG demand opportunity is not uniform across Southeast Asia, and the country-level picture reveals where it is most pronounced.
Singapore’s grid runs on approximately 95% gas today, meaning virtually every new data centre megawatt translates almost directly into incremental LNG offtake. With piped imports from Malaysia and Indonesia expected to cease by the early 2030s, the city-state’s LNG reliance is on course to reach 100%.
Malaysia and Thailand offer the biggest chance for growth. Both are seeing steady drops in domestic and piped gas supply, making LNG the only fuel option to support new gas power plants. Malaysia has 3.9 GW of data centre capacity under development, with new regasification terminals being built to meet growing power demand. Thailand, where two-thirds of the grid is already gas-fired, is expected to see its LNG share of gas supply exceed 50% by 2035 as Gulf of Thailand production and Myanmar pipeline imports continue to fall.
Indonesia (Batam) is emerging as the third node of the Singapore-Johor-Riau (SIJORI) corridor, with over 450 MW in the pipeline and strong policy support supporting its data centre ambitions. The binding constraint is power deliverability – grid reliability remains a concern at the scale of incoming demand.
"Malaysia and Thailand are at a turning point. Data centre investment is growing quickly just as domestic gas output peaks and declines." Omarali added. "New import infrastructure is being developed and the importer base is broadening. For LNG suppliers with volumes to place, this timing is important."
South Asia: scale without substance for LNG
India’s data centre market is set to grow fivefold to nearly 12 GW by 2035, making it the second largest in Asia Pacific and attracting an estimated US$145 billion in investment between 2024 and 2030. Despite this scale, Wood Mackenzie finds that LNG is structurally unable to capture the opportunity.
LNG-to-power generation costs two to three times more than renewables paired with battery storage in India, making gas economically unviable as a baseload fuel for data centres. Gas currently accounts for under 2% of India’s power generation mix and is forecast to remain at that level through the outlook period, as coal and renewables continue to dominate. Pipeline infrastructure gaps across key data centre corridors in southern, central and eastern India add a further barrier to gas penetration.
None of India’s hyperscalers have announced gas-backed power supply agreements, with the commercial and industrial renewable power purchase agreement market having already exceeded 33 GW of contracted data centre capacity.
Pakistan and Bangladesh present further constraints, with persistent load-shedding, grid instability and macroeconomic pressures limiting data centre demand and deterring hyperscale investment.
Read the article online at: https://www.worldpipelines.com/business-news/07092026/wood-mackenzie-data-centre-boom-drives-structural-lng-demand-in-southeast-asia-while-south-asia-remains-out-of-reach/